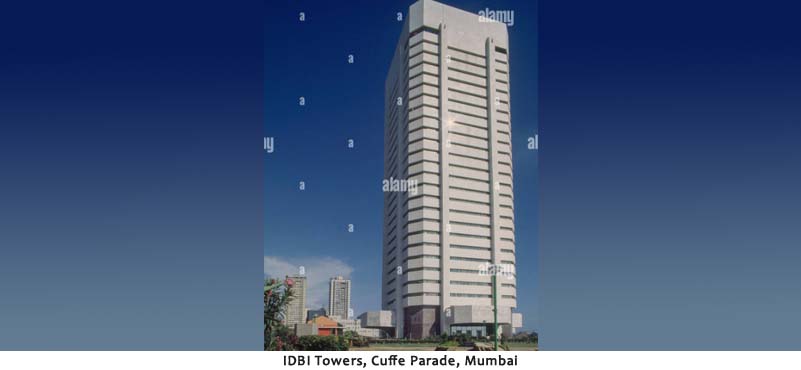
The central government’s proposed divestment of IDBI Bank represents a welcome addition to non-debt capital receipts, though its broader fiscal significance remains constrained. Of the anticipated ₹88,000–89,000 crore aggregate from disinvestment and asset monetisation, the vast majority is already built into the ₹80,000 crore budget target for FY27. The genuine fiscal upside is roughly ₹8,000–9,000 crore—capable of absorbing revenue gaps or expenditure overruns, but insufficient to alter the sovereign’s underlying fiscal trajectory. A thorough evaluation of the transaction requires assessing three distinct dimensions: immediate fiscal impact, public balance-sheet management, and the long-term governance implications of transferring managerial control.
Transaction and Receipts
On October 14, 2026, the Cabinet Committee on Economic Affairs (CCEA) approved Fairfax-backed Canada Inc. as “the strategic buyer” for a 60.72% stake in IDBI Bank, involving consideration of approximately ₹52,878 crore. The transaction comprises the government’s 30.48% holding and Life Insurance Corporation of India’s 30.24% holding. Following completion, the government and LIC would retain 15% and 19%, respectively. Crucially, Cabinet approval is not the same as completed disinvestment: regulatory compliance, transaction documentation and receipt of payment remain material milestones. The distinction between the two sellers is important. Approximately ₹26,500 crore would accrue to the Union government; the balance belongs to LIC. Although LIC is government-controlled, its proceeds cannot simply be counted as Union Budget receipts. The sale of the government’s shares in LIC, which generates receipts for the Centre, is a different transaction from LIC selling its own investment in IDBI Bank.
Disinvestment and asset monetisation had mobilised ₹62,124 crore by September 10. The Centre expects IDBI proceeds to take the combined amount to about ₹88,700 crore. There is also a broader projection of ₹90,000 crore–₹1 lakh crore, conditional on completion and further transactions. These are alternative receipt scenarios based on evolving circumstances, not interchangeable estimates or realised collections.
Placed in a broader comparative context, this decision represents the latest in a series of substantial foreign direct investments in the domestic financial sector. Earlier this year, Emirates NBD acquired a 60% controlling stake in RBL Bank for approximately $3 billion, alongside Mitsubishi UFJ Financial Group’s $4.4 billion acquisition of a 20% stake in Shriram Finance. This follows Sumitomo Mitsui Banking Corporation’s acquisition of 24.2% in YES Bank in 2025 for just under $2 billion. Furthermore, the strategic restructuring of IDBI Bank continues the central government’s systematic disinvestment trajectory, following previous transactions including Air India, Neelachal Ispat Nigam Limited, Ferro Scrap Nigam Limited, and Indian Medicines Pharmaceuticals Corporation Limited.
Impact of Additional Receipts
Under India’s budgetary presentation, disinvestment proceeds enter non-debt capital receipts. Other things remaining unchanged, higher receipts reduce the fiscal deficit—the difference between total expenditure and receipts excluding borrowing—and the associated financing requirement. The budgeted FY27 fiscal deficit is ₹16,95,768 crore, conventionally rounded to ₹16.96 lakh crore, or 4.3% of GDP. Against this, an ₹8,000 crore overshoot represents approximately 0.47% of the deficit. Using the GDP denominator implicit in the rounded Budget ratio, it amounts to roughly 0.02 percentage points of GDP, or two basis points. Even the approximately ₹8,700 crore excess implied by receipts of ₹88,700 crore would produce only a marginal change in the headline ratio.
These higher scenarios do not invalidate the primary premise. Achieving receipts of ₹90,000 to ₹100,000 crore yields an incremental surplus of ₹10,000 to ₹20,000 crore, translating to a minor deficit reduction of 0.03–0.05 percentage points of GDP. A fundamental distinction exists between fulfilling budgeted revenue assumptions and securing unexpected windfalls. Additionally, these additional receipts may not directly reduce public borrowing, as they could instead cushion revenue shortfalls, subsidy pressures, or supplementary appropriations.
Significance of Cushion
According to the latest Controller General of Accounts (CGA) data for April–August 2026, the fiscal deficit reached roughly ₹7.10 lakh crore—against a full-year target of ₹16.96 lakh crore—backed by ₹12.92 lakh crore in revenue receipts and ₹5.10 lakh crore in capital spending. While the CGA warns against extrapolating these early figures into full-year projections due to timing mismatches, spending patterns already point to real fiscal pressure.
Fertiliser subsidies are a clear strain: by August, urea subsidy spend reached ₹77,522 crore (of the budgeted ₹1,16,799 crore) and nutrient-based subsidies hit ₹25,617 crore (out of ₹54,000 crore). Together, they consumed nearly 60% of their annual allocation in just five months. Front-loaded disbursements and settlement cycles may account for some of this surge, so an overrun isn’t guaranteed, but it requires tight oversight.
Rising fertiliser costs and fuel excise-duty cuts are placing additional pressure on the fiscal position. Higher asset-monetisation receipts and proceeds from the IDBI Bank sale may help absorb the resulting subsidy burden, but their contribution will remain limited. These one-off gains can provide a useful buffer against expenditure pressures; they cannot eliminate the wider uncertainties surrounding fiscal management.
A Stronger Year, But an Uneven Programme
The government’s 6.5% stake sale in LIC generated ₹31,515 crore—more than half the disinvestment receipts reported by September 10. Other significant transactions included Coal India, NHPC, General Insurance Corporation, Hindustan Copper and Central Bank of India. The improvement has, therefore, depended substantially on minority stake sales in listed enterprises. Such sales can broaden ownership and realise value without relinquishing control. They should not, however, be confused with privatisation or enterprise restructuring. Selling a small additional holding does not by itself alter management incentives or operational performance. IDBI is different because the proposed transaction transfers management control to a strategic investor.
It is contextually significant that exceeding the original receipts target would be the first such outcome since FY2018–19, when disinvestment receipts reached ₹84,972 crore against an ₹80,000 crore target. This would mark an important execution improvement. Yet dependence on a few large transactions remains a vulnerability: approval delays, regulatory conditions or adverse markets can move substantial receipts across financial years. A credible medium-term fiscal framework should not rely on every major transaction closing precisely on schedule.
Valuation: Beyond the Sale Price
A fiscal deadline must not become the overriding determinant of valuation. The government’s account of the IDBI process provides grounds for both reassurance and scrutiny. The accepted offer of ₹81 per share exceeded the revised benchmark valuation of ₹75.99. Two professional agencies assessed value using relative-valuation and asset-valuation approaches. However, an earlier reserve price of ₹94.42 had not attracted acceptable bids. The government subsequently excluded the volatile market price from its valuation exercise, arguing that narrow trading could disconnect quoted prices from intrinsic value.
These circumstances alone do not show whether the bank was undervalued, or the government secured a good deal. That judgment depends on the assumptions behind the valuation, including how asset quality, property holdings, profitability and liabilities were assessed. There must be a clear explanation of how these factors shaped the accepted price. An earlier stock-market peak is not, by itself, a useful benchmark. The government must weigh the proceeds from selling now against the dividends it would forgo, the investment risks it would avoid and any further capital it might otherwise have to provide. The sale should leave public finances stronger over time, rather than simply help meet this year’s receipts target.
One-Off Receipts and Lasting Fiscal Capacity
Asset sales improve the cash deficit without necessarily improving the government’s underlying net worth. Equity ownership is exchanged for cash; the economic outcome depends on the price received and the use of that cash. Using proceeds to finance productive infrastructure, retire debt or avoid damaging investment cuts can generate lasting benefits. Using them repeatedly to accommodate an expanding recurrent expenditure base creates a mismatch: a finite stock of assets finances continuing obligations.
The scale of those obligations is substantial. FY27 interest payments are budgeted at approximately ₹14.04 lakh crore, against revenue receipts of ₹35.33 lakh crore—nearly 40%. The Centre’s debt-to-GDP ratio is budgeted at 55.6%, compared with 56.1% in the preceding year’s revised estimate. These figures demonstrate why durable consolidation in conformity with the glide path envisaged in the Fiscal Responsibility and Budget Management (FRBM) Act depends on revenue strength, spending efficiency and sustained growth, rather than occasional asset-sale windfalls.
It is important to realise that disinvestment receipts can lower the fiscal deficit without directly reducing the revenue deficit, which measures the excess of revenue expenditure over revenue receipts. They therefore cannot, by themselves, correct a fundamental disequilibrium in the government’s current account.
Banking Governance and Private Control: Ownership Change Is the Beginning
The main value of privatising IDBI Bank is not a quick boost to government revenue, but the opportunity to build a more accountable and disciplined bank. However, this shift is not guaranteed. Changing ownership from public to private hands does not automatically ensure better performance. I have clearly brought out in my series of papers on consolidation of banks that the evidence regarding privatisation of banks is mixed; privatisation alone does not guarantee better performance. The litmus test is whether the new management improves efficiency, strengthens accountability and operates within an effective regulatory framework.
The proposed transaction would give the Fairfax-backed purchaser a 60.72% shareholding, while the government and LIC would retain 15% and 19%, respectively. Significantly, the announced arrangements envisage neither the government nor LIC retaining a board seat. The successful bidder must also satisfy the RBI’s regulatory requirements and submit a roadmap for compliance with the conditions prescribed during the ownership assessment. These provisions make the transaction a substantive transfer of managerial authority rather than simply another minority stake sale.
Commercial Autonomy Must Be Matched by Accountability
Private control can streamline decision-making, sharpen leadership incentives, and drive smarter capital allocation. A strategic investor is often better equipped to upgrade technology, bring in specialised talent, streamline expenses, and refocus business units on long-term profitability. Yet these benefits are far from guaranteed. They hinge entirely on the buyer’s investment horizon, management strength, and willingness to inject fresh capital.
True autonomy requires a balance: bank management must be free from political interference to reject unsound loans, but it cannot be free from oversight. Replacing political pressure with favoritism toward a new owner’s business network is not progress—the goal is professional banking, not swapping one form of influence for another. Therefore, the true test of privatisation is governance: Are credit decisions based strictly on independent risk assessment? Does the board get bad news promptly? Are executives held accountable for hiding poor performance? Because a bank can look profitable for years while quietly accumulating bad loans, evaluating a sale requires looking at long-term stability, not just quick profit gains.
Board Must Be Independent of the Controlling Shareholder
A controlling investor provides a clear centre of responsibility but also concentrates power. The board must represent the bank’s interests as an institution rather than function as an extension of the promoter’s office. For IDBI Bank, this requires directors with credible expertise in credit, treasury, technology, cyber resilience, human resources and regulatory compliance. Independence should be demonstrated through conduct: questioning aggressive growth assumptions, scrutinising large exposures, challenging provisioning judgments and resisting transactions whose principal beneficiary is the controlling shareholder. The audit and risk committees should receive information directly from the relevant control functions. The chief risk officer, compliance head and internal audit leadership should have protected access to these committees, without depending exclusively on the chief executive. Remuneration should reward risk-adjusted performance over several years rather than loan-book expansion or short-term profitability. This emphasis is consistent with the RBI’s ownership framework, which seeks diversified ultimate ownership and control and requires major shareholders to remain “fit and proper” on a continuing basis. Regulatory suitability is therefore an ongoing obligation, not a clearance obtained once at acquisition.
Related-party Risks Require Vigilance
The ownership structure of a financial group can create conflicts across lending, investment, procurement, distribution and information sharing. These risks warrant particular attention where the controlling shareholder has interests in other financial institutions or businesses. Fairfax’s existing investment in CSB Bank makes the eventual structure of its Indian banking interests an important regulatory question. Contemporary reporting identifies potential restructuring choices, but these should not be treated as settled decisions. Any eventual arrangement must be assessed against the RBI’s conditions, operational feasibility and the interests of depositors and minority shareholders—not simply the purchaser’s preference.
For IDBI, the practical safeguards should include comprehensive identification of connected entities, independent scrutiny of transactions involving the wider shareholder group, and reporting systems capable of detecting indirect exposures. Procurement contracts, insurance distribution arrangements and technology services deserve scrutiny alongside loans. Conflicts can arise through fees, preferential access or data use even where no conventional lending relationship exists. India’s banking framework requires prior RBI approval for major share acquisitions and continuing monitoring of shareholder suitability. These requirements provide an essential regulatory foundation; the bank’s own controls must make them effective in daily operations.
Residual Public Ownership Must Not Blur Responsibility
The government and LIC’s combined residual holding of 34% creates a transitional ownership structure. Their announced withdrawal from board representation can help separate public shareholding from operational management. But minority ownership must not become an informal route for directing credit, appointments or commercial decisions. Conversely, private management should not interpret the continuing public stake as an assurance of future taxpayer support.
A clear accountability framework should distinguish three roles: the government as shareholder, the RBI as regulator and the board as the body responsible for the bank’s direction. Confusing these roles would weaken the very rationale for transferring control. Public disclosures should also explain material shareholder arrangements and the treatment of minority investors. With the government retaining authority to sell its residual holding through the prescribed process, the transition should be managed transparently rather than leave markets guessing about future ownership.
Employees, customers and inclusion are part of the reform
The authorities have stated that employee service conditions will remain unchanged and pension benefits are fully funded. These assurances provide an important starting point, but a successful transition requires more than reassurance at the point of sale. Management should communicate clearly about organisational restructuring, performance assessment, redeployment and reskilling, particularly as technology changes branch operations and staffing needs.
Involving employees doesn’t have to slow down reform. Poorly managed change fuels uncertainty, which damages morale, drives away experienced staff, and harms customer relationships. A phased, collaborative transition helps retain institutional knowledge while boosting productivity. Private ownership, however, doesn’t relieve a bank of its public responsibilities—priority-sector lending rules and RBI supervision still apply. The real challenge for policymakers is fulfilling these obligations efficiently without compromising sound lending standards. Financial inclusion and commercial discipline can—and should—coexist.
Judge the Reform over a Full Credit Cycle
The true success of IDBI Bank’s strategic sale depends on long-term financial and operational strength, not the initial purchase price. As my decades of research on Indian economic reforms (over 100 papers and 7 books) consistently show, performance must be evaluated across an entire credit cycle by tracking new bad loans, recoveries, provisioning, capital buffers, interest margins, and liquidity resilience—alongside non-financial metrics like customer complaints, cybersecurity, IT outages, and related-party transparency. Ultimately, profitability cannot be judged in isolation from risk.
IDBI’s experience underscores the importance of institutional reform. The Reserve Bank of India placed the bank under Prompt Corrective Action (PCA) in May 2017 and lifted restrictions in March 2021 following improvements in its financial position. Its subsequent rehabilitation, supported by capital and institutional backing, should not be confused with the proposed ownership transition. Private management may sharpen accountability, but durable gains depend on underwriting discipline, independent risk oversight and effective RBI supervision.
Post-sale monitoring should examine concentration risks, connected lending, large corporate exposures, employee retention, depositor confidence and continuity of customer services. The residual government and LIC shareholdings also demand clear boundaries between ownership, operational management and regulation. Moreover, acquiring existing shares transfers ownership; it does not automatically inject fresh capital into the bank. Future capital requirements must therefore be assessed independently.
Given the centrality of fiscal prudence, sale receipts should be recognised only when realised, with transparent reporting of proceeds against budget estimates. The Centre must distinguish outright disinvestment from asset monetisation and avoid double-counting resources. As Mir Taqi Mir wrote eloquently,
“राह–ए–दूर–ए–इश्क़ में रोता है क्या
आगे आगे देखिए होता है क्या”
English translation
Why weep on the long and arduous road of love?
Wait and see what unfolds as we journey on.
The true test of IDBI’s privatisation lies in its performance under new ownership: whether it sharpens credit allocation, safeguards depositors, competes more aggressively, and operates without government backstops. Closing the transaction is merely the beginning. Its enduring value will be determined by strong governance, financial resilience, and disciplined lending. As an editorial in The Economic Times (“IDBI, poster boy for more privatisation”, Oct 15, 2026) succinctly summed up, “Success should pump energy into India’s stalled privatisation of banks. GOI’s greatest disinvestment coup could set the template for a stronger banking industry”. Amen!
ABOUT THE AUTHOR
 Dr. Manoranjan Sharma has been the Chief Economist for 25 years with Canara Bank and Infomerics Ratings.
Globally recognised as an expert in global economy, Indian economy, banking, finance, MSMEs, sustainable development and financial inclusion, he has chaired sessions at national and international conferences and is recognised as one of the 30 global experts by the UN Virtual University (UNVU) for SDGs.
He has been on over a dozen Advisory Councils in seven states, viz. Member, Rajasthan Governor’s Advisory Council; Governor’s Senate Nominee on Rajasthan University; Governor’s Senate Nominee on SNDT University, Mumbai; and Expert on selection panels for IIMs, Vijay Patil School of Management, SAIL, IDBI Bank, Canara Bank, Bank of India, Union Bank of India.
He has been published widely and quoted extensively in major Indian and international media and publications.